
Commercial Auto Insurance in Dallas, TX: Requirements, Cost & Who Needs It
If you drive for work — a box truck, a contractor pickup, a delivery van, or even your own car — your personal policy may not cover you. Here’s what Texas requires, what it costs in 2026, and how to get covered before the busy season.
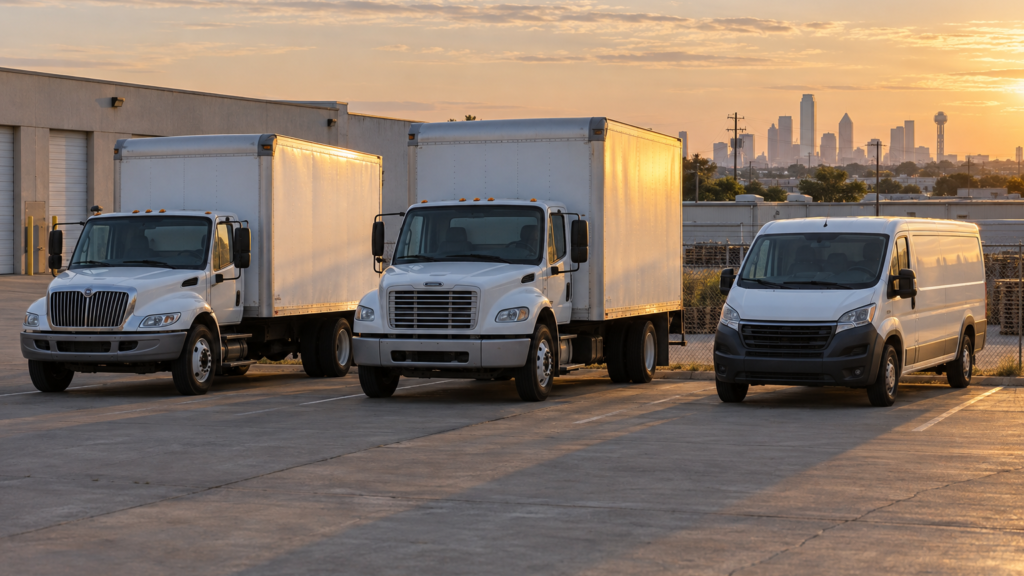
Commercial auto insurance in Dallas, TX covers the vehicles you use to run your business — box trucks, vans, contractor pickups, and company cars — with higher liability limits and business-use protection that a personal auto policy flatly excludes.
What Is Commercial Auto Insurance?
Commercial auto insurance in Dallas, TX is a business policy that covers vehicles used for work. It looks similar to personal auto coverage on paper — liability, collision, comprehensive — but it is built for higher limits, heavier vehicles, multiple drivers, and the business exposure that comes with hauling tools, cargo, or customers.
The critical difference is the one most owners find out too late: a personal auto policy contains a business-use exclusion. If you are hauling materials to a job site, making deliveries, or driving a vehicle titled to your LLC, your personal insurer can deny the claim outright — leaving you paying for the other driver’s injuries and your own truck out of pocket. Our business insurance page covers the full picture.
Commercial vs. Personal Auto at a Glance
- Who is covered — the business entity, not just one named person.
- Who can drive — employees and scheduled drivers, not only household members.
- Higher limits — often $500,000 to $1,000,000, well above the personal minimum.
- Business use is covered — hauling, delivering, and job-site driving are expected, not excluded.
- Add-ons personal policies don’t offer — cargo, hired and non-owned auto, on-hook towing.
Who Needs It in Dallas — 7 Clear Signs
You do not need a fleet to need commercial coverage. One truck and one employee is enough. If any of these describe you, your personal policy is almost certainly the wrong policy:
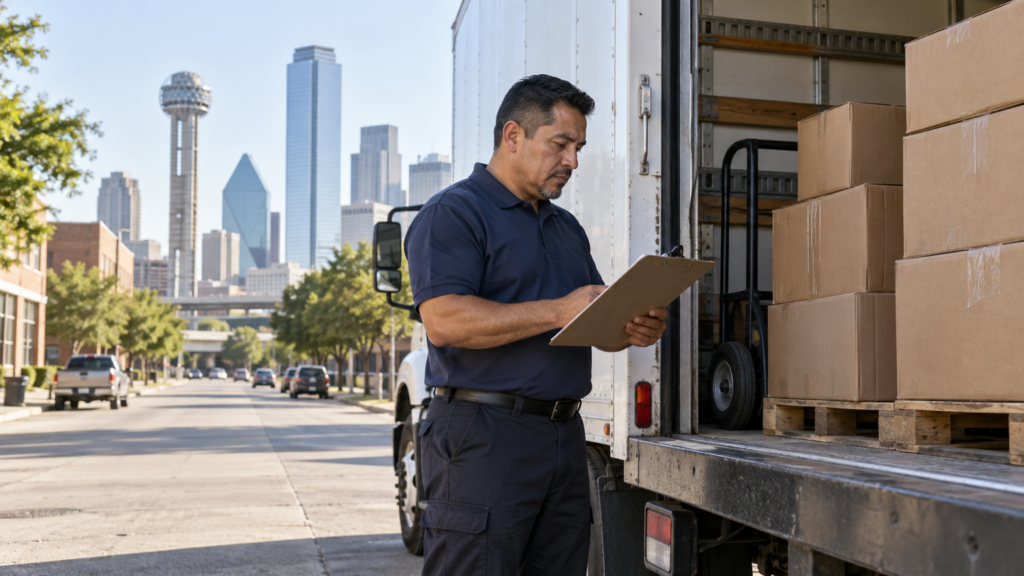
You likely need commercial auto if…
- The vehicle is titled or registered to a business or LLC.
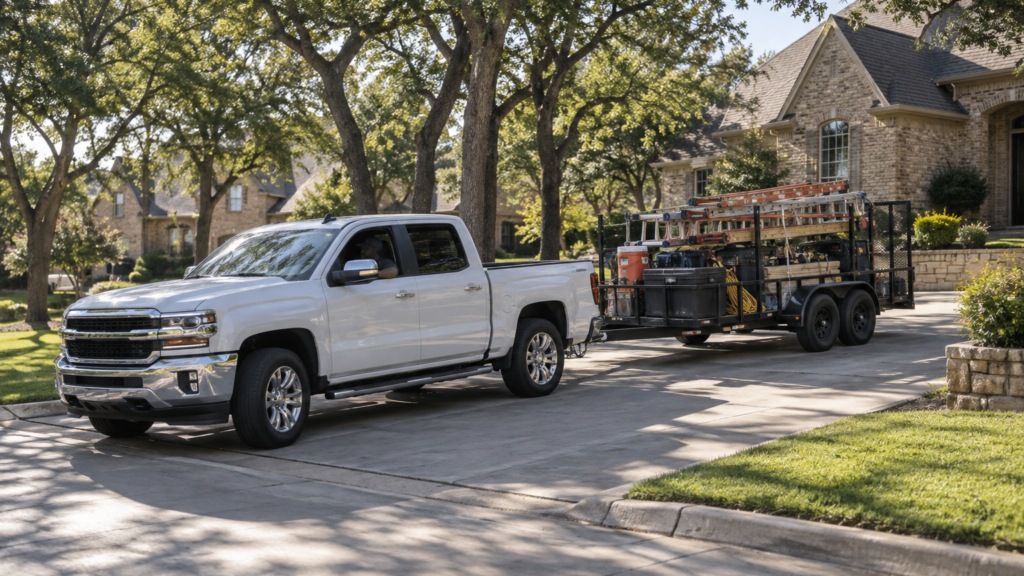
- You haul tools, equipment, or materials to job sites.
- You make deliveries — food, packages, parts, or freight.
- Employees drive the vehicle, not just you and your family.
- The vehicle has a GVWR over 10,000 lbs, a utility bed, or a permanent rack.
- You tow a trailer for work.
- A client or general contractor requires a certificate of insurance before you can start.
The gig-driver gray zone
Driving for Uber, Lyft, DoorDash or Amazon Flex sits between personal and commercial. Most of those drivers need a rideshare or delivery endorsement rather than a full commercial policy — but the one thing that never works is assuming your standard personal policy covers the app being on.
Fourth quarter is when this gets expensive
Holiday delivery contracts and end-of-year construction push more Dallas work trucks onto the road between October and December than any other stretch of the year. A denied claim in the middle of your busiest season can close a small business. Verify your coverage before the season starts, not after a crash.
Texas Commercial Auto Requirements & Limits
Texas sets a floor, and your vehicle’s weight and where you drive push that floor higher. There are three tiers Dallas business owners need to know:
Standard commercial vehicles — 30/60/25
Every vehicle on a Texas road, commercial or not, must carry at least $30,000 per injured person, $60,000 per accident, and $25,000 in property damage. This is the legal minimum for vans, pickups, and light box trucks — and it is far too low for most businesses.
Over 26,000 lbs GVWR, Texas-only routes — $500,000
Intrastate for-hire carriers running heavier trucks must carry a minimum $500,000 combined single limit. Hauling certain hazardous materials raises it further.
Crossing state lines — $750,000 FMCSA minimum
The moment your route leaves Texas for hire, federal FMCSA rules apply and the floor jumps to $750,000 in liability — $1,000,000 or more for many commodities.
Texas minimums are still 30/60/25 — don’t believe otherwise
You will find Texas agency sites claiming the state minimum rose to 50/100/40. It did not. HB 4178 died in committee on March 31, 2025 and was never passed. The legal minimum in Texas remains 30/60/25. Anyone quoting you off the higher number is working from bad information.
Meeting the minimum and being adequately covered are two different things. A single injury claim from a commercial vehicle accident routinely exceeds $30,000, and your business assets are what pays the difference. Most Dallas contractors and delivery operations we write land at $500,000 to $1,000,000 in liability, often paired with general liability and an umbrella policy.
What Commercial Auto Insurance Covers
A commercial policy is modular. You build it from these pieces:
✅ Core coverages
- Liability — injuries and property damage you cause to others. The part the law requires.
- Collision — repairs to your truck after an accident, regardless of fault.
- Comprehensive — theft, vandalism, fire, and the hail that North Texas delivers every spring.
- Uninsured/underinsured motorist — critical here, since roughly 1 in 7 Texas drivers carries no insurance at all. See our uninsured motorist guide.
- Medical payments / PIP — injuries to you and your passengers.
➕ Business-specific add-ons
- Hired and non-owned auto — covers rented trucks and employees running errands in their own cars. The single most commonly missed coverage.
- Motor truck cargo — the freight or goods you are hauling.
- Trailer interchange — trailers you pull but do not own.
- Rental reimbursement and downtime — keeps you earning while the truck is in the shop.
Hail is a commercial problem too
Dallas–Fort Worth is the most hail-prone metro in the country, and a lot parked with six work trucks is six claims in one storm. Only comprehensive pays for hail — see how it works in our hail damage coverage guide.
How Much Commercial Auto Insurance Costs in Dallas (2026)
There is no flat rate — a landscaping pickup and a refrigerated box truck are different risks. As a 2026 working range for the Dallas–Fort Worth market:
Typical annual premium ranges
- Contractor pickup or work van — roughly $1,800 to $3,500 per vehicle.
- Light delivery van — roughly $2,500 to $5,000 per vehicle.
- Box truck (Class 3–6, non-CDL, local) — roughly $4,500 to $9,000 for liability plus physical damage.
- Heavy or interstate trucking — $12,000 and up, driven by cargo and radius.
What actually moves your rate
- Radius of operation — local Dallas routes price far better than long-haul.
- Driver records — your MVRs are underwritten individually; one bad record can reprice the whole policy.
- Vehicle weight and value — GVWR and replacement cost.
- Cargo — what you haul and what it is worth.
- Limits and deductibles — raising a deductible is usually the fastest legitimate savings.
- Claims history — three clean years is real money.
At GI Auto Insurance we shop multiple commercial carriers to find the real number for your operation — with no broker fees. Request your free quote and we’ll price it against several markets.
How to Get Covered in Dallas Today
Most Dallas businesses can be bound the same day, and we can issue a certificate of insurance while you wait:
Gather your vehicle and driver list
VINs, year/make/model, GVWR, and a driver’s license number for everyone who will drive.
Tell us your radius and cargo
How far you run and what you haul are the two biggest pricing levers. Be accurate — a misstated radius is how claims get denied.
Compare limits side by side
We quote the state minimum next to $500,000 and $1,000,000 so you can see what the real protection costs. It is usually less than owners expect.
Bind and get your certificate
Same-day coverage and a certificate of insurance emailed to your general contractor or client — start your free quote.
No SSN? No problem.
We write business owners using a passport, matrícula consular, ITIN, or foreign license. No credit check, no broker fees, and se habla español. Call (214) 352-1600 or visit any of our three Dallas offices.
Frequently Asked Questions
Get your trucks covered before the busy season
Free commercial auto quote from our Dallas team — multiple carriers compared, no broker fees, same-day certificates of insurance.
Get My Free Quote