
Flood Insurance in Dallas, TX: What It Covers, the 30-Day Wait and Who Needs It
One heavy fall storm can put a foot of water in a Dallas living room, and a standard homeowners policy will not pay for any of it. Here is how flood coverage works in North Texas, why you cannot buy it the day the forecast turns, and what protects your car.
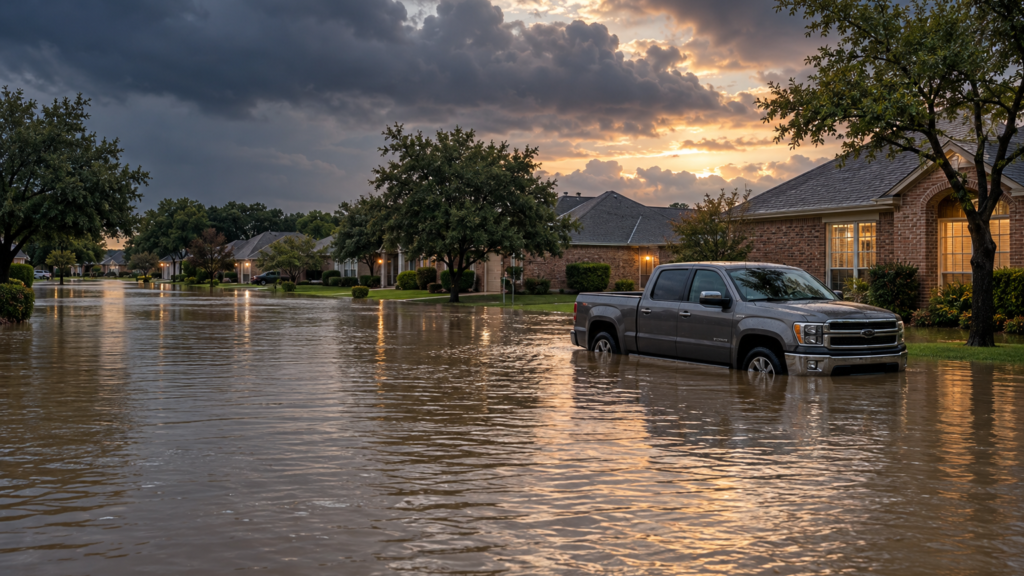
Flood insurance in Dallas, TX is a separate policy, because standard homeowners and renters insurance in Texas does not cover flood damage at all. It usually takes 30 days to start, so the time to buy it is before storm season, not while the radar is red. This guide covers what it pays for, who really needs it, and how flood damage to your car is handled.
Why Dallas Homes Flood (Even Outside a Flood Zone)
Most people picture flooding as a coastal problem. In Dallas it is mostly flash flooding: several inches of rain in a few hours, falling on concrete, rooftops and dry clay soil that cannot soak it up. The water goes to the lowest street, the closest creek, and sometimes through your front door.
Fall is part of that pattern. In October 2015, four to seven inches of rain fell across Dallas, Tarrant, Johnson and Ellis counties and caused flash flooding serious enough for swift water rescues. Spring brings the bigger storm season from April through June.
What drives flood risk in DFW
- Creeks and low crossings: neighborhoods near the Trinity River and its many creeks see water rise fast.
- Pavement and new construction: more concrete means more runoff in streets that were dry ten years ago.
- Dry, cracked clay soil: after a drought, rain runs off instead of soaking in.
- Overwhelmed storm drains: water backs up into streets, garages and yards.
A flood zone map is not a guarantee
FEMA says more than 20% of flood insurance claims come from properties outside high-risk flood zones. Being in a low or moderate risk zone means flood coverage usually costs less, not that you do not need it.
Your Homeowners Policy Does Not Cover Flooding
This is the part that surprises people the most. A standard Texas homeowners policy, a renters policy and a landlord policy all exclude flood. If rising water comes in from outside, the claim is denied unless you have a separate flood policy.
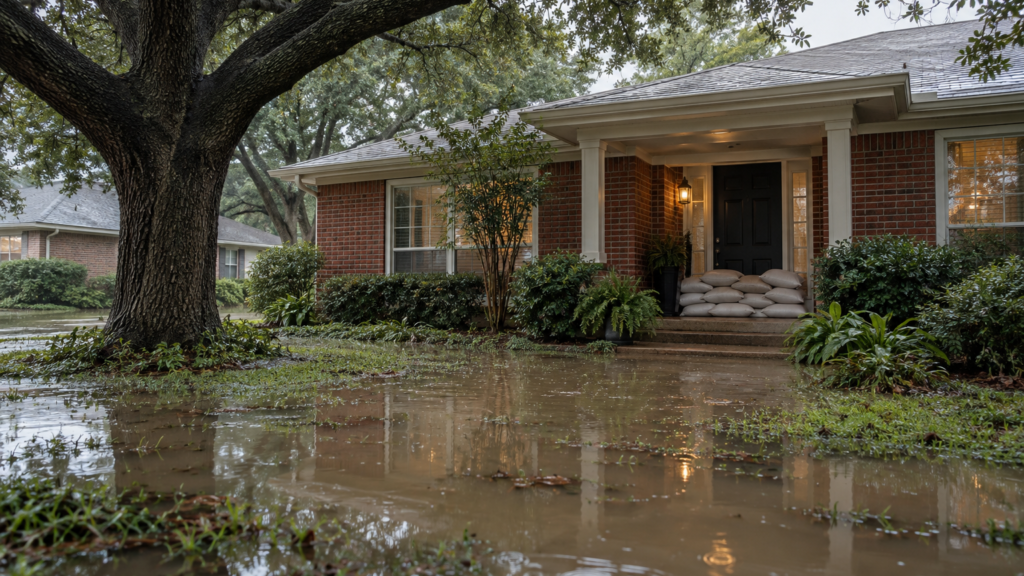
Flood vs. water damage: the difference that decides your claim
- Flood (needs a flood policy): surface water from heavy rain, an overflowing creek, or water flowing in from the street or yard.
- Sudden water damage (usually covered by homeowners): a burst pipe, a broken water heater, or a washing machine hose that fails.
- Rain through storm damage (usually covered by homeowners): wind or hail opens the roof and rain comes in through the hole.
We covered the rest of what a homeowners policy does and does not pay for in our guide to home insurance in Dallas.
What Flood Insurance Covers
Most flood policies are written through the National Flood Insurance Program (NFIP), run by FEMA and sold by agencies like ours. There are also private flood policies, which can offer higher limits or shorter waiting periods.
The two parts of an NFIP policy
- Building coverage: the structure, foundation, electrical and plumbing, HVAC, water heater, built-in appliances, permanently installed carpet and cabinets. Up to $250,000 for a home.
- Contents coverage: furniture, clothing, electronics and portable appliances. Up to $100,000, and it is bought separately from building coverage.
- Renters can buy contents-only flood coverage for their belongings.
- Not covered: cars (that is your auto policy), money and valuables, most items in a basement, landscaping, fences and pools.
Check that you bought both parts
A common mistake is buying building coverage only. If the water ruins your couch, your mattresses and your TV, building coverage does not pay for them. Ask us to show you both lines on the quote.
The 30-Day Waiting Period: Why Timing Matters
An NFIP flood policy normally takes effect 30 days after you buy it. The rule exists so people cannot wait until a storm is in the forecast. If the flood comes on day 20, the claim is not paid.
The standard rule: 30 days
Applies when you buy a new NFIP policy on your own.
The loan exception
No waiting period when the flood policy is required to make, increase, extend or renew a mortgage, for example at closing.
Private flood policies
Some private carriers start coverage in about 10 to 14 days, and a few sooner. The terms vary by company, so we compare them side by side.
Buy in the fall, not in May
Dallas storm season peaks from April to June. A policy bought in October or November is fully active long before then. A policy bought the week the storms start is not.
What If Your Car Gets Flooded?
Flood insurance does not cover vehicles. Water damage to your car is paid by the comprehensive part of your auto insurance, after your deductible. Liability-only coverage, the Texas 30/60/25 minimum, pays nothing for your own car.
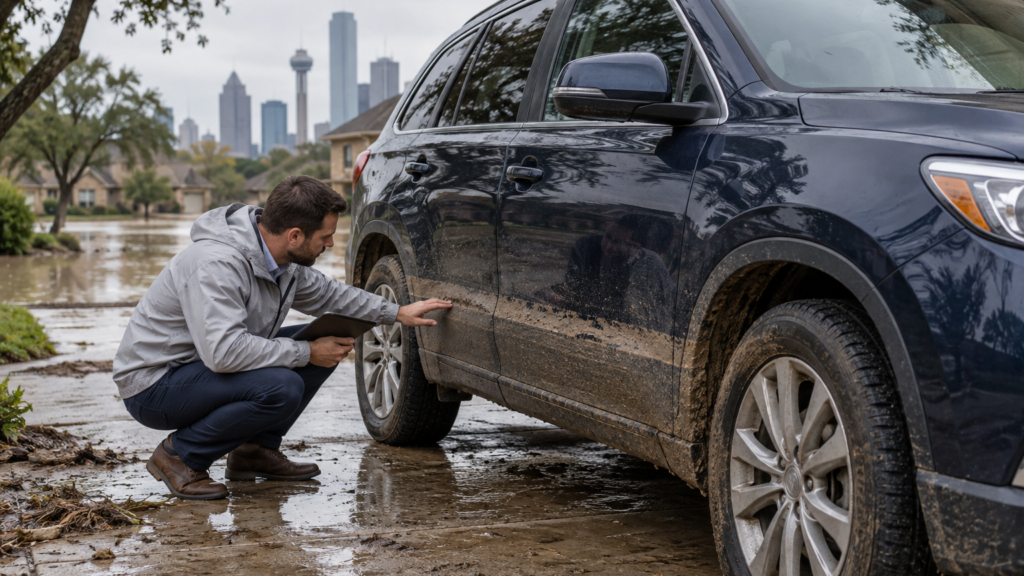
If your car sat in water
- Do not start the engine. Water in the engine can turn a repairable car into a total loss.
- Take photos of the water line inside and outside before anything is moved.
- Call your agent the same day so the claim is opened and the car can be towed and dried.
Turn around, do not drown
The National Weather Service warns that about 12 inches of moving water can carry away most cars, and 2 feet can sweep away SUVs and trucks. Most flood deaths happen in vehicles. If water covers the road, find another way.
If you only carry liability today, this is a good time to price comprehensive. It is the same coverage that pays for hail damage and theft. See our comparison of full coverage vs. liability in Texas.
How to Get Flood Insurance in Dallas
Getting a quote takes a few minutes, and we do it in English or Spanish.
Tell us about the property
Address, year built, whether you own or rent, and whether there is a mortgage. We look up the flood zone for you.
Compare NFIP and private options
We show building and contents coverage side by side, with the waiting period of each option written out.
Bundle what makes sense
Review your homeowners or renters policy and your car’s comprehensive coverage at the same time, so there are no gaps between them.
One agency for the whole household
Flood, home, renters and auto in one place, no broker fees. Visit one of our three Dallas offices, call (214) 352-1600, or start your free quote online.
Frequently Asked Questions
Get covered before the next storm season
Free quotes on flood, home and auto insurance with no broker fees. Se habla español.
Get My Free Quote